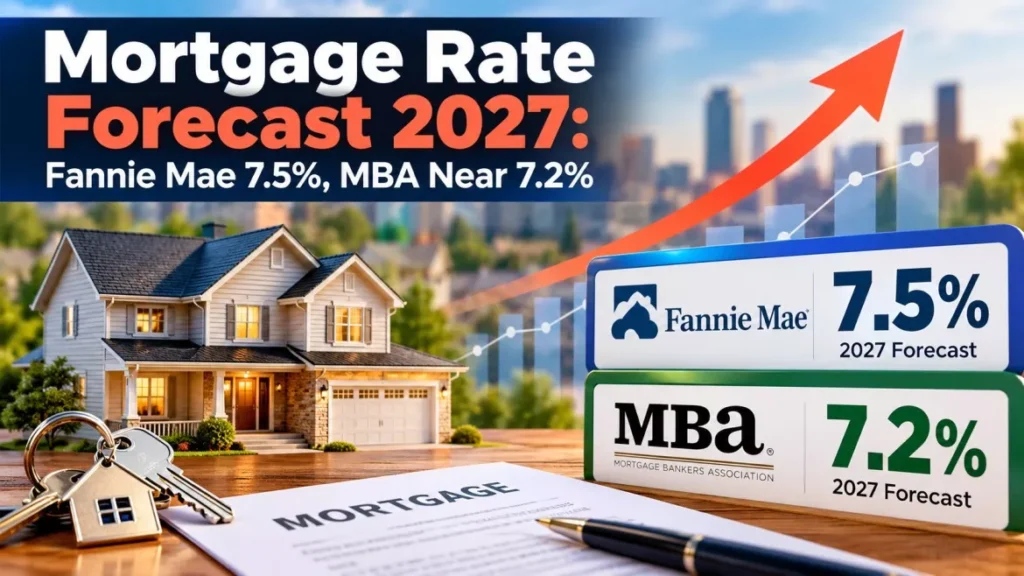
The mortgage rate forecast 2027 from Fannie Mae now reads 7.5%, up from 6.7%. The United States mortgage finance company published the revision in its October 2026 Housing Forecast on 14 October, and expects that rate in all four quarters of next year. The Mortgage Bankers Association’s own baseline sits lower, nearer 7.2%.
What Fannie Mae Changed on 14 October
The revision is 0.8 percentage points on the 2027 figure, one of the sharpest single-month changes Fannie Mae has made to that number. It also lifted its fourth-quarter 2026 projection to 7.4% from 6.8%.
Fannie Mae is the government-sponsored enterprise that buys conforming mortgages from United States lenders and packages them into securities, so its forecast feeds the volume assumptions lenders plan around. The figures below are all for the 30-year fixed-rate mortgage, the standard American home loan.
- Fourth quarter 2026: 7.4%, raised from 6.8% in the September forecast.
- Each quarter of 2027: 7.5%, raised from 6.7%.
- Single-family originations, 2026: about $2.08 trillion.
- Single-family originations, 2027: about $1.86 trillion, which Scotsman Guide reported is more than 18% below the $2.28 trillion Fannie Mae had forecast a month earlier.
- Purchase lending, 2027: about $1.43 trillion, cut 2.8% from the prior forecast.
Those two origination numbers are often conflated. Measured year on year, 2027 lending falls about 11% from 2026. Measured against what Fannie Mae itself said in September, the 2027 figure is down more than 18%. The first is a housing-market forecast; the second is the size of the forecaster’s own change of mind.
Where the Forecast Sits Against Today’s Rate
As of 19 October 2026, the most recent official United States reading is 7.40% for a 30-year fixed loan, unchanged on the week in Freddie Mac’s weekly survey published on 15 October 2026. The 15-year fixed average eased to 6.71% from 6.73%.
A year earlier the same survey put the 30-year rate at 6.27% and the 15-year at 5.52%. Fannie Mae’s 7.5% projection therefore assumes the market stays roughly where it already is rather than easing, which is a change from forecasts published as recently as September.
One detail most coverage left out: Mortgage Professional America reported that Fannie Mae built the October forecast on rate levels as of 30 September, and that daily lender averages had already reached 7.46% by 13 October. Weekly survey averages and daily lender quotes are different measurements and routinely differ by a tenth of a point or more. Our earlier report on mortgage rates at 7.40% set out that gap in detail.
Fannie Mae and the MBA Do Not Agree
The two most-watched United States forecasts now point in the same direction but not to the same place. The Mortgage Bankers Association, the trade body for American mortgage lenders, published its own October outlook with rates above 7% through 2027 but below Fannie Mae’s line.
| Measure (United States, 2027) | Fannie Mae, 14 October 2026 | MBA, October 2026 |
|---|---|---|
| 30-year fixed rate | 7.5% every quarter | 7.2% for the first three quarters, 7.1% in the fourth |
| Total originations | About $1.86 trillion | $1.99 trillion |
| Purchase lending | About $1.43 trillion | $1.42 trillion, up 0.8% |
| Refinance volume | $430 billion | $571 billion |
The two bodies are close on purchase lending and about $141 billion apart on refinancing. That is the whole of the disagreement: they differ on how many existing borrowers will find a reason to replace their loan, not on how many people will buy a house.
Why Refinancing Carries the Revision
Refinancing is replacing an existing mortgage with a new one, usually to cut the interest rate or take out equity. It is the part of lending that responds fastest to a rate move, which is why a forecast revision lands on it hardest.
Fannie Mae now projects refinance volume falling from $655 billion in 2026 to $430 billion in 2027, with refinancing’s share of all originations dropping from 31% to 23%, according to Mortgage Professional America’s reading of the forecast. Against September’s forecast, the 2027 refinance figure is down more than 46%.
Joel Kan, the MBA’s vice president and deputy chief economist, told HousingWire: “With rates in the 7% to 7.5% range, it’s just very difficult for anyone to really find that justification to refi.” His colleague Mike Fratantoni, the MBA’s chief economist and senior vice president for research and business development, said of hopes for a sharp fall in rates: “I don’t think we’re going to come down that far.” Refinancing volumes had already dropped sharply through the autumn, as our report on the 30-year rate reaching 7.28% recorded.
What Could Move the Forecast Next
Two scheduled United States events fall inside the next ten days, and both sit upstream of the mortgage rate.
- Thursday 22 October 2026: Freddie Mac publishes its next weekly Primary Mortgage Market Survey, the reading that sets the official 30-year average.
- Tuesday 27 and Wednesday 28 October 2026: the Federal Reserve’s rate-setting committee meets. The current target range is 3.75% to 4.00% after the 16 September increase, the first since 2023, which we covered in our report on the September Fed rate hike.
The Federal Reserve does not set mortgage rates. Long-term home loans track the 10-year Treasury yield and the spread lenders add on top of it. Scotsman Guide reported that Fannie Mae’s October forecast assumes a 10-year yield of about 5.3% at the end of 2026 and through 2027, up from the 4.8% it assumed in September, and a federal funds rate of 4.3% in the first quarter of 2027 rising to 4.4%.
What remains undecided is whether those assumptions hold. Fannie Mae also cut its 2027 house price forecast to a 0.6% rise from 2.7% in 2026, per Mortgage Professional America, and September inflation came in at 3.7% over 12 months. None of the forecasts above is a commitment, and all of them are revised monthly.
Frequently Asked Questions
What Is the Mortgage Rate Forecast for 2027?
Fannie Mae’s October 2026 Housing Forecast, published on 14 October, projects a United States 30-year fixed rate of 7.5% in every quarter of 2027. The Mortgage Bankers Association’s October outlook is lower, at about 7.2% for most of the year.
Does the Forecast Say What Rate an Individual Borrower Will Pay?
No. These are national averages for a 30-year fixed conforming loan. An individual quote depends on credit profile, loan size, down payment, property type, lender and state, and can sit well above or below the average.
When Is the Next Official United States Mortgage Rate Reading?
Freddie Mac publishes its Primary Mortgage Market Survey every Thursday. The next release is due on 22 October 2026, following the 7.40% reading of 15 October 2026.
Why Did Fannie Mae Raise Its Forecast?
The October forecast assumes higher Treasury yields and a higher federal funds path than the September version did, with the 10-year yield assumption moving to about 5.3% from 4.8%, according to Scotsman Guide.
What Happens to Refinancing if Rates Stay Near 7.5%?
Fannie Mae projects United States refinance volume falling to $430 billion in 2027 from $655 billion in 2026, cutting refinancing’s share of all mortgage lending from 31% to 23%.