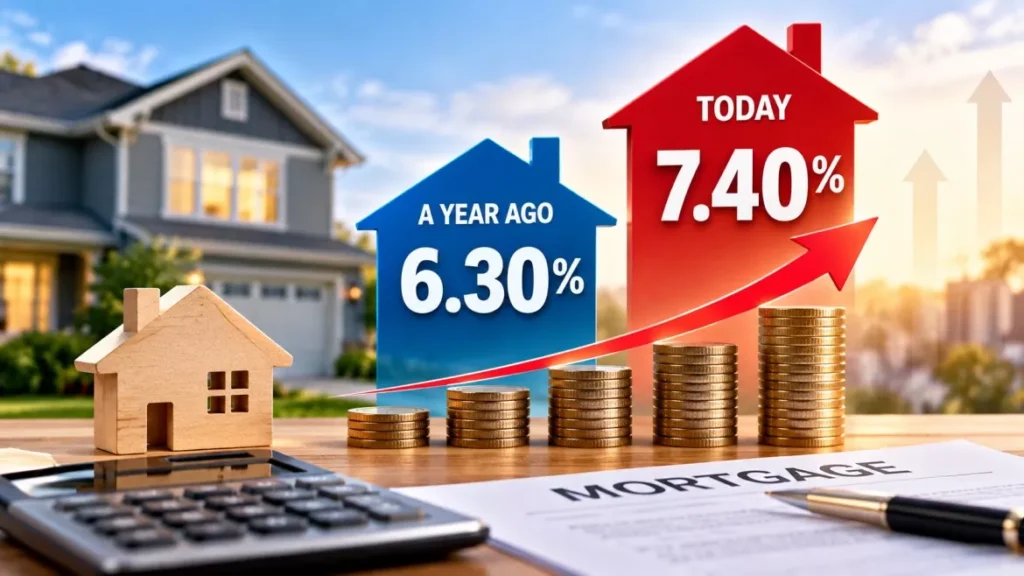
Mortgage rates today in the United States stand at 7.40% for a 30-year fixed loan, published by Freddie Mac in its weekly survey on 8 October 2026. That is up from 7.28% a week earlier and 6.30% a year ago, a seventh consecutive weekly rise. Freddie Mac put the 15-year fixed average at 6.73%.
What the 8 October Survey Reported
Freddie Mac’s Primary Mortgage Market Survey, the weekly national benchmark published every Thursday by the United States government-sponsored mortgage buyer, put the 30-year fixed average at 7.40% and the 15-year fixed average at 6.73% for the week ending 8 October 2026.
Both figures rose by roughly an eighth of a percentage point on the week. The 30-year average gained 0.12 percentage points from the previous week’s 7.28% reading, and the 15-year gained 0.13 percentage points from 6.60%.
- 30-year fixed, week to 8 October 2026: 7.40%, against 7.28% a week earlier and 6.30% a year earlier.
- 15-year fixed, week to 8 October 2026: 6.73%, against 6.60% a week earlier and 5.53% a year earlier.
- Consecutive weekly increases: seven.
As of 10 October 2026, 7.40% is the highest 30-year reading in Freddie Mac’s weekly survey since November 2023. The Associated Press described the level as the highest in nearly three years. All of these figures describe the United States market only; they do not apply to mortgages in the United Kingdom, India, Australia or anywhere else.
Why Several Different Mortgage Rates Are Circulating This Week
More than one number is in print for the same week because the main trackers measure different things over different periods. None of them is wrong, and they are not interchangeable.
| Series | Reading | As of | What it measures |
|---|---|---|---|
| Freddie Mac PMMS, 30-year fixed | 7.40% | Week to 8 October 2026 | Weekly average drawn from mortgage applications submitted to Freddie Mac by lenders nationwide |
| Freddie Mac PMMS, 15-year fixed | 6.73% | Week to 8 October 2026 | The same series, on a 15-year term |
| Mortgage News Daily index, 30-year fixed | 7.48% | 9 October 2026 | A daily reading of lender rates, which moves before the weekly average catches up |
The daily figure runs ahead of the weekly one by design. Freddie Mac’s survey window covers application activity from the previous Thursday through Wednesday, so a Thursday publication is already describing a period that has closed. Mortgage News Daily’s index stood at 7.48% on 9 October 2026, eight basis points above the weekly survey average. A basis point is one hundredth of a percentage point.
Who the 7.40% Average Actually Describes
The 7.40% figure is a conditional average, not a quote, and it describes a narrow borrower. Freddie Mac states that the survey “is focused on conventional, conforming, fully amortizing home purchase loans for borrowers who put 20% down and have excellent credit”.
Each of those conditions excludes a large share of the market. Conventional means not insured by a government programme such as the Federal Housing Administration or the Department of Veterans Affairs. Conforming means within the loan-size limits set for the two mortgage agencies. Fully amortising means the payment retires the loan over its term. The survey also covers purchase loans rather than refinancing, and it does not include points or fees, which borrowers may pay on top of the quoted rate.
A borrower with a smaller deposit, a lower credit score, a jumbo loan, a government-backed loan or a refinance is therefore looking at a different number. The average is a measure of where the market sat that week, not an offer, and the rate any individual is quoted depends on credit history, deposit size, loan type, property type and location.
What a Year of Increases Does to a $400,000 Loan
The 110-basis-point gap between this week’s average and last October’s is the figure that shows up in a monthly payment. The table below applies the survey averages to a $400,000 30-year loan, covering principal and interest only.
| 30-year rate | As of | Monthly principal and interest on $400,000 |
|---|---|---|
| 6.30% | Week to 9 October 2025 | About $2,476 |
| 7.28% | Week to 1 October 2026 | About $2,737 |
| 7.40% | Week to 8 October 2026 | About $2,770 |
The difference between the two Octobers is about $294 a month, or roughly $3,500 a year, on that loan size. These are calculations from the published survey averages, not lender quotes, and they exclude property taxes, homeowners insurance, mortgage insurance, points and closing costs, all of which a real monthly payment includes.
What Is Pushing Rates Higher
Mortgage rates in the United States track the 10-year Treasury yield rather than the Federal Reserve’s policy rate, and that yield has been climbing since late September. The 10-year averaged 5.28% over the survey week, nine basis points above the previous week, and traded near 5.22% on the afternoon of 8 October 2026.
Joel Berner, senior economist at Realtor.com, attributed the move to “a wicked brew of inflation expectations, a broad bond market selloff” and rising fiscal deficits pushing yields higher, in comments reported by Fox Business. He said high rates “have the housing market spooked”.
The Federal Reserve does not set mortgage rates directly. Its most recent minutes showed staff do not expect inflation to return to 2% until 2029. Its decisions feed into expectations for inflation and growth, which move Treasury yields, which in turn move mortgage pricing — a chain that can leave mortgage rates rising even in a week when the policy rate does not change.
What the Market Looks Like at 7.40%
Demand indicators have weakened alongside the increase, though the readings come from different weeks and different surveys. Pending home sales fell year on year in both August and September 2026, according to Realtor.com data reported by Fox Business.
The same reporting said sellers have been cutting asking prices at a pace not seen in four years, with for-sale inventory up 5.4% year on year. These are single-outlet figures drawn from one brokerage data set, and they describe the national picture rather than any local market.
What Happens Next
Freddie Mac publishes its next weekly survey on Thursday 15 October 2026. Because the series is weekly and the daily indexes move every business day, the 7.40% reading is a snapshot of the week to 8 October and not a standing figure.
Nothing in the survey tells a borrower where rates go from here. Freddie Mac publishes the reading without a forecast, and the direction from mid-October depends on Treasury yields, which respond to inflation data and bond-market conditions rather than to the mortgage market itself.
Frequently Asked Questions
What Is the Mortgage Rate Today in the United States?
Freddie Mac’s weekly survey put the 30-year fixed average at 7.40% for the week ending 8 October 2026. Mortgage News Daily’s daily index read 7.48% on 9 October 2026. Both are United States national averages.
Why Is Freddie Mac’s Rate Lower Than the Rate a Lender Quotes?
The survey covers conventional, conforming purchase loans for borrowers with a 20% deposit and excellent credit, and it excludes points and fees. Borrowers outside that profile, and anyone refinancing, are quoted on a different basis.
How Long Have Mortgage Rates Been Rising?
The 30-year average rose for a seventh consecutive week in the survey published on 8 October 2026. It has gone from 6.30% in the same week of 2025 to 7.40%.
Does the Federal Reserve Set Mortgage Rates?
No. Fixed mortgage rates in the United States move with the 10-year Treasury yield, which averaged 5.28% during the week to 8 October 2026. Federal Reserve decisions influence that yield but do not set mortgage pricing.
Where Are the Official Figures Published?
Freddie Mac publishes the Primary Mortgage Market Survey on its own website each Thursday at noon eastern time, with the next release due on 15 October 2026.