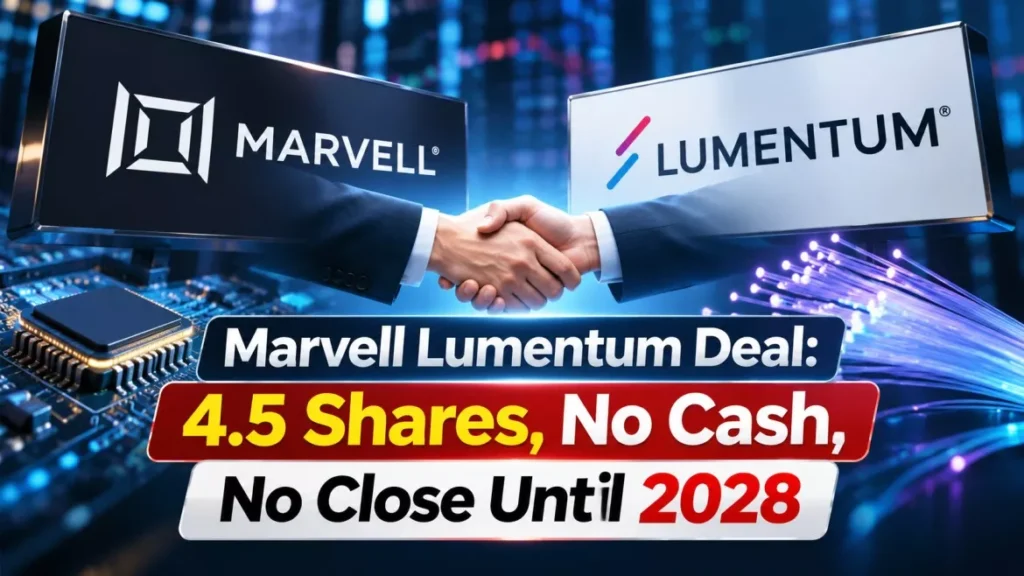
The Marvell Lumentum deal will pay Lumentum shareholders entirely in Marvell stock, at a fixed 4.500 shares each. That implied about $1,132 a Lumentum share when the two Nasdaq-listed US companies announced terms on 2 November 2026, valuing Lumentum at $115 billion including debt. Closing is not expected until the first half of 2028.
Marvell Technology, the US chip designer, and Lumentum Holdings, the US maker of lasers and optical components, both trade on Nasdaq. As of 3 November 2026, the deal is a signed agreement and nothing more. No shareholder has voted, no competition regulator has cleared it, and the merger agreement filed with the United States Securities and Exchange Commission sets a first deadline of 1 November 2027, with extensions available into August 2028. Both companies continue to operate separately until closing.
Why the Deal Has No Fixed Price
The $115 billion figure is not a price Marvell will pay in cash. This is an all-stock transaction, meaning Lumentum investors are paid in newly issued Marvell shares rather than money, at a fixed exchange ratio of 4.500 Marvell shares for each Lumentum share.
Because the ratio is fixed and the share count is not, the value of the consideration moves with Marvell’s share price every trading day. The $1,132 per Lumentum share implied at announcement reflects Marvell’s price at that moment, not a guaranteed sum. The companies put the premium at approximately 23.9% over the unaffected closing prices of 28 October 2026, which it describes as the last trading day before market speculation about a transaction began.
| Term | Detail |
|---|---|
| Consideration | All stock, no cash component |
| Exchange ratio | 4.500 Marvell shares per Lumentum share (fixed) |
| Implied value per Lumentum share | About $1,132 at announcement, 2 November 2026 |
| Premium | About 23.9% to unaffected prices of 28 October 2026 |
| Implied enterprise value | About $115 billion |
| Ownership after closing | Marvell holders about 67%, Lumentum holders about 33%, fully diluted |
| Expected close | First half of calendar 2028 |
Where the $115 Billion Figure Comes From
Different numbers have circulated because they measure different things, and the companies and news outlets have not used them interchangeably.
Marvell’s own announcement states an implied enterprise value of $115 billion. Enterprise value counts the target’s equity plus its net debt, so it describes the whole business rather than the sum paid to shareholders. Reuters reported the equity value, the portion attributable to Lumentum’s shareholders, at about $102.5 billion. A note to Lumentum staff from its chief executive referred to roughly $100 billion, according to reporting on the company’s filings.
| Figure | What it measures | Source |
|---|---|---|
| About $115 billion | Implied enterprise value, including net debt | Marvell and Lumentum joint announcement, 2 November 2026 |
| About $102.5 billion | Equity value attributable to Lumentum shareholders | Reuters, 2 November 2026 |
| About $100 billion | Figure used in an internal note to Lumentum staff | Reported from company filings |
Outlets also differed on whether the transaction sets a record. Fox Business described it as the largest merger between two publicly traded companies, and Axios as the largest merger between public technology companies. Bloomberg was reported as calling it the year’s largest by equity value. The companies themselves made no record claim in their announcement.
What Marvell Shareholders Give Up
Marvell is paying with roughly a third of itself. On a fully diluted basis, which counts shares that could be issued under options and similar awards, existing Marvell holders will own about 67% of the combined company and former Lumentum holders about 33%.
That dilution is why Marvell investors get a vote at all. Marvell must ask its own shareholders to approve both the issuance of the new shares and an amendment to its corporate charter, the governing document that sets out matters including the number of shares the company is authorised to issue.
Marvell says the combination gives it line of sight to more than $1 billion in annual run-rate cost synergies, meaning recurring savings measured at an annualised pace once fully achieved, and that it expects the deal to add to Marvell’s non-GAAP earnings per share in the first year after closing. It puts the combined company’s addressable market at $550 billion. Those are company projections for a business that will not exist for at least 18 months.
Why Both Share Prices Fell on 2 November
Both stocks dropped on the day the deal was announced, an unusual reaction for a target carrying a 23.9% premium. CNBC reported Marvell down 13% and Lumentum down nearly 19% on Monday 2 November 2026. Reporting by Fortune carried the same figures. TheStreet cited intraday falls of roughly 10% for Marvell and 15% for Lumentum, so the figure depends on the point in the session being measured.
The fall in Lumentum is explained by the structure. Because holders are being paid in Marvell shares, a drop in Marvell mechanically reduces what the deal is worth to them, and they also carry the risk that it never completes. Fortune, citing Motley Fool reporting, attributed the selling to a view among investors that Marvell overpaid. Both stocks had risen sharply beforehand: CNBC reported that Marvell had more than doubled over the prior year and Lumentum had roughly quadrupled.
Analyst opinion split rather than converged. Stifel cited the deal terms in a note on Lumentum, Raymond James argued the market reaction was overdone, and B. Riley pointed to dilution and integration risk at Marvell. Shares in other optical suppliers, including Ciena and Coherent, also fell, which one report linked to broader selling across AI-related stocks rather than to the deal alone.
The Votes and Clearances Still Outstanding
Six things have to happen before the deal can close, according to the companies’ filings with the Securities and Exchange Commission:
- A registration statement: Marvell must file a Form S-4 covering the new shares and have it declared effective by the Securities and Exchange Commission.
- A Lumentum shareholder vote: Lumentum stockholders must adopt the merger agreement.
- Two Marvell shareholder votes: Marvell stockholders must approve both the share issuance and the charter amendment.
- United States antitrust clearance: The waiting period under the Hart-Scott-Rodino Act, the US law requiring large deals to be notified to competition authorities before completion, must expire or be terminated.
- Other regulatory approvals: Certain further clearances are required. The filings do not name the jurisdictions.
- Listing and closing conditions: Nasdaq must authorise the new shares for listing, and customary conditions on representations, warranties and the absence of a material adverse effect must be met.
No shareholder meeting date has been set, and no regulator has published a review timetable. Multi-jurisdiction clearances are what stretch timetables in deals of this size, as the Emera and Canadian Utilities all-share merger showed when it required approval in four countries.
The merger agreement’s own deadline differs from the guidance in the press release. The filings set an outside date, the point at which either side may walk away, as follows:
- 1 November 2027, 11:59pm Pacific Time: The initial outside date.
- 1 February 2028: First extension, available where required regulatory approvals are still pending.
- 1 May 2028: Second extension on the same basis.
- 1 August 2028: Third and final extension on the same basis.
The companies publicly guide to a close in the first half of calendar 2028. Reporting on the Lumentum staff note described a window of roughly 12 to 18 months, which is shorter than the filed guidance. Readers comparing the two should note that the press release and the merger agreement are answering different questions: one states an expectation, the other sets a legal deadline.
What a Collapse Would Cost
The merger agreement filed with the Securities and Exchange Commission prices the risk of failure in three separate fees, and the amounts indicate which risks the parties considered real. A termination fee is a sum one party owes the other if the deal ends for specified reasons.
- $5.8 billion: Payable by Marvell if its board withdraws its recommendation or it accepts a superior proposal.
- $2.9 billion: Payable by Lumentum in reciprocal circumstances.
- $3.2 billion: Payable by Marvell as a regulatory termination fee, if the deal fails on competition or foreign-investment grounds or is not completed by the outside date with all other conditions met.
The agreement states that Marvell cannot be required to pay both the general and the regulatory fee, and that neither fee is payable more than once. The $3.2 billion regulatory fee is the figure to watch, because it is the one that falls due if clearances rather than cold feet end the transaction. By comparison, the Salesforce acquisition of Braze announced in October 2026 carried a regulatory break fee of $300 million on a far smaller deal.
Where Nvidia Fits In
Nvidia holds stakes in both companies without being party to the merger. It announced a $2 billion investment in Marvell on 31 March 2026 alongside a data-centre partnership, and CNBC has listed Lumentum among earlier recipients of $2 billion Nvidia investments. The publicly filed merger agreement does not name Nvidia as a party.
Bloomberg reported that Marvell chief executive Matt Murphy and Lumentum chief executive Michael Hurlston sought Nvidia chief executive Jensen Huang’s view by telephone before the announcement, citing people familiar with the matter. That account rests on Bloomberg’s sourcing; Nvidia has not published a statement on the deal. Hurlston told Fox Business that Nvidia’s reaction had been “super positive”.
The arrangement feeds an existing criticism that Nvidia is investing in companies that in turn buy from it or supply it. Murphy rejected that framing in comments to CNBC, calling the transaction “a double down on supporting Nvidia”.
What Is Still Unknown
The filings leave several questions open. Which jurisdictions beyond the United States must clear the deal has not been disclosed, nor has any regulator’s timetable. No shareholder meeting dates exist yet. Whether competition authorities will seek conditions is unknown, and commentary has pointed to the position of transceiver makers that buy Marvell’s digital signal processors and would, after closing, be buying from a direct competitor in optical components.
The companies have not published combined revenue figures, and the cost-synergy and earnings projections are forecasts for a business that cannot legally exist before 2028. Marvell’s share price between now and then determines what Lumentum shareholders actually receive.
Questions About the Marvell Lumentum Deal
What Is the Marvell Lumentum Deal Worth?
Marvell’s announcement of 2 November 2026 gives an implied enterprise value of about $115 billion, which includes Lumentum’s net debt. Reuters reported the equity value, the part attributable to shareholders, at about $102.5 billion. Because the deal is paid in Marvell shares at a fixed ratio, the value changes with Marvell’s share price.
What Will Lumentum Shareholders Receive?
Each Lumentum share converts into 4.500 Marvell shares, with cash paid in place of fractional shares. There is no cash alternative. The exchange ratio is fixed, so the amount received in Marvell stock does not change, but its market value does.
When Will the Marvell Lumentum Deal Close?
The companies expect to close in the first half of calendar 2028. The merger agreement sets an outside date of 1 November 2027, extendable to 1 February, 1 May and 1 August 2028 while required regulatory approvals remain pending.
What Approvals Does the Deal Still Need?
It needs a Lumentum shareholder vote, two Marvell shareholder votes covering the share issuance and a charter amendment, expiry of the US Hart-Scott-Rodino antitrust waiting period, certain other regulatory approvals that the filings do not name, an effective Form S-4 and Nasdaq listing authorisation. No meeting dates or regulatory timetables have been published.
Why Did Marvell and Lumentum Shares Fall?
CNBC reported Marvell down 13% and Lumentum down nearly 19% on 2 November 2026. Fortune, citing Motley Fool reporting, attributed the selling to a view that Marvell overpaid; Lumentum holders are also exposed to Marvell’s share price and to the risk the deal does not complete. Analysts disagreed on whether the reaction was justified.
Is Nvidia Part of the Marvell Lumentum Deal?
No. Nvidia holds investments in both companies, including a $2 billion stake in Marvell announced on 31 March 2026, but the publicly filed merger agreement does not name it as a party. Bloomberg reported that both chief executives sought Jensen Huang’s view before announcing, citing people familiar with the matter.