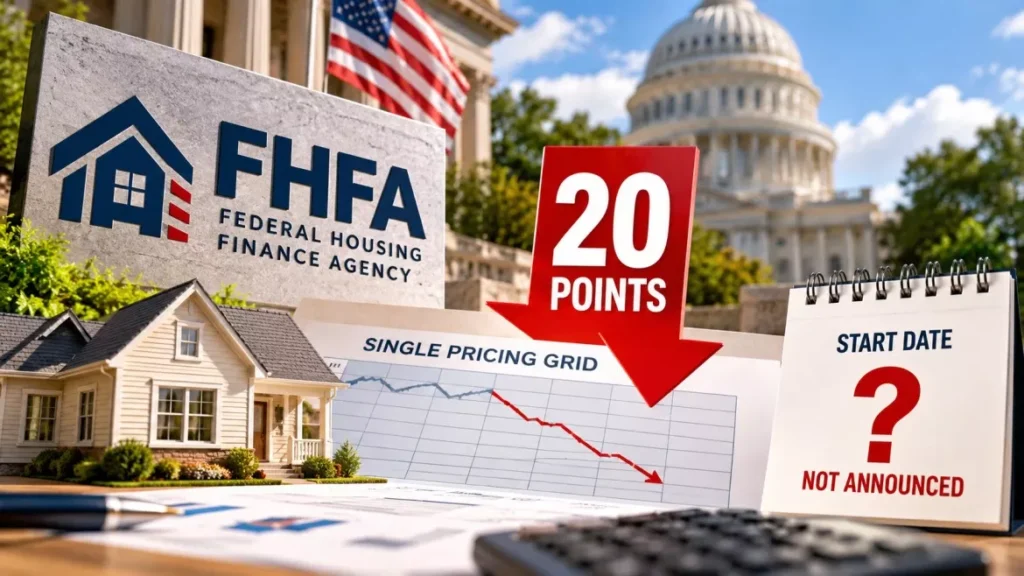
The Federal Housing Finance Agency has put VantageScore 4.0 on the same mortgage pricing grid as Classic FICO. Director Bill Pulte announced the FHFA single pricing grid on X late on Monday, ending a 20-point penalty that applied to VantageScore on United States conventional loans. FHFA has published neither the grid nor a start date.
What the Single Pricing Grid Changes
The change removes a handicap that had made VantageScore 4.0 more expensive for borrowers than its raw number suggested. Both models now feed the same loan-level price adjustment table.
A loan-level price adjustment, or LLPA, is the fee Fannie Mae and Freddie Mac add to a loan based on risk factors, including the borrower’s credit score. A lower score band means a higher fee, which lenders generally pass through to the borrower as a higher rate or a larger charge at closing.
Until this week, the two models sat on separate grids. VantageScore 4.0 scores were shifted 20 points downward before the fee was worked out, so a VantageScore of 800 was priced as though it were a Classic FICO score of 780, according to HousingWire’s account of the grids the two companies published. The single grid removes that step.
Pulte set out the decision in a post on X. “We are Simplifying Mortgage Pricing following feedback from lenders and consumers,” he wrote. “Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid.” He did not attach a grid or a date.
Why FICO Shares Fell About 26%
Investors read the change as the end of a protected position rather than a technical adjustment. Fair Isaac Corporation, which owns FICO, closed down about 26% at roughly $618 on Tuesday 29 September 2026, its steepest one-day fall in more than two years.
The reason sits in what each score costs a lender. FICO’s wholesale price for a mortgage score rose to $10 for 2026, from $4.95 in 2025. TransUnion has said it will hold standalone VantageScore 4.0 mortgage pricing at $0.99 per score through December 2028. On a three-bureau pull, that difference is repeated three times on every application.
| Classic FICO | VantageScore 4.0 | |
|---|---|---|
| Owner | Fair Isaac Corporation | Jointly owned by Equifax, Experian and TransUnion |
| Wholesale price per mortgage score | $10 for 2026, up from $4.95 in 2025 | $0.99 through December 2028, per TransUnion |
| Share of originations, August 2026 | The long-standing default | 5.6% |
| Pricing grid before this week | Its own grid | Separate grid, scores cut by 20 points first |
Fannie Mae and Freddie Mac together support about 70% of the United States mortgage market, so their choice of scoring model effectively sets the industry standard. FICO’s Scores segment is its most profitable, and mortgage origination fees charged per score pull are a large part of it.
Fair Isaac had already drawn political attention over that pricing. Senator Josh Hawley opened an inquiry into the company in March 2026 and asked federal competition regulators to examine whether the increases were anticompetitive.
What FHFA Has Not Published
The most important detail is still missing: nobody outside FHFA knows what the single grid actually says. As of 1 October 2026, the agency has published neither the unified single-family pricing grid nor an implementation date for United States conventional loans, which leaves the effect on any individual borrower’s costs unresolved.
Three things remain undecided on the public record:
- The grid itself: the fee bands that will apply to each score range have not been released.
- The start date: Pulte’s post gave no date, and no implementation schedule has followed.
- Loans already in progress: how applications priced under the old grids will be treated has not been addressed.
Lenders could already choose VantageScore 4.0 for eligible loans before this announcement, so the practical question is pricing rather than permission. Borrowers with questions about which model a lender uses would find that on the lender’s own disclosures rather than in the announcement.
The Contradiction With FHFA’s Own September Grids
The single grid reverses a judgement the agency made about two weeks earlier. On 10 September 2026, FHFA opened VantageScore 4.0 delivery to all lenders, and Fannie Mae and Freddie Mac published official grids that kept the 20-point downward adjustment in place.
That adjustment existed because the models score the same borrower differently. Jaret Seiberg of TD Cowen described the new arrangement as effectively an across-the-board cut in loan-level pricing, and pointed out that FHFA had concluded only weeks before that VantageScore overstated credit quality by roughly 20 points against FICO. Removing the adjustment without replacing the analysis behind it is the part the agency has not explained.
Analysts also flagged a second-order effect. Ashish Sabadra of RBC raised the prospect of score shopping, where a lender runs both models and submits whichever produces the better band. With the pricing handicap gone, there is no longer a built-in reason to prefer one model’s number over the other’s.
Which Loans This Applies To
This is a United States change, and a narrow one within that market. It covers conventional conforming loans bought or guaranteed by Fannie Mae and Freddie Mac, the two government-sponsored enterprises FHFA regulates.
It does not reach loans insured by the Federal Housing Administration or guaranteed by the Department of Veterans Affairs, jumbo loans held on lenders’ own books, or mortgage markets outside the United States, which use their own scoring and pricing systems. Terms also vary by lender, so two borrowers with the same score can be quoted differently.
For context on what borrowers are paying while this is settled, the 30-year Treasury yield and mortgage rates have both been climbing through September, and a fuller explanation of how the scores themselves are built sits in our guide to FICO credit score ranges.
Frequently Asked Questions
What Is the FHFA Single Pricing Grid?
It is one loan-level price adjustment table used for both Classic FICO and VantageScore 4.0 on United States conventional loans bought by Fannie Mae and Freddie Mac. FHFA Director Bill Pulte announced it on X late on Monday, replacing two separate grids.
When Does the Single Pricing Grid Take Effect?
No date has been published. As of 1 October 2026, FHFA has not released an implementation schedule or the grid itself.
Was the 20-Point VantageScore Adjustment Removed?
Yes. Under the separate grids published on 10 September 2026, VantageScore 4.0 scores were reduced by 20 points before pricing was calculated. The single grid ends that step.
Why Did FICO Stock Fall?
Fair Isaac Corporation closed down about 26% at roughly $618 on Tuesday 29 September 2026. The single grid removes the pricing disadvantage that had discouraged lenders from choosing VantageScore 4.0, whose per-score cost is far lower than FICO’s $10 wholesale mortgage price for 2026.
Does This Change Mortgage Costs Outside the United States?
No. FHFA regulates Fannie Mae and Freddie Mac, which operate only in the United States. Other countries use their own credit scoring models and lender pricing rules.